A biblical budget is a stewardship-shaped spending plan that puts generous giving, essential obligations, and future preparation ahead of lifestyle wants, and the reader can begin tonight by writing down take-home income and monthly bills. This approach brings order, peace, and a clear channel for generosity rather than guilt. We walk through the theology, the categories, and the exact steps a household or couple can put into practice right away.
TL;DR:
- Record monthly take home income and every recurring or irregular expense, then allocate money to giving, obligations, needs, savings, daily living, and discretionary spending.
- Set aside a $1,000 starter emergency fund before extra debt payments; after consumer debt is paid down, build savings toward three to six months of expenses.
- Divide annual bills by 12 and save that amount monthly, preferably through automatic transfers, so insurance premiums or holiday giving do not disrupt the budget.
- Review spending monthly and broader trends quarterly; revisit categories if the cash buffer shrinks or debt rises for two consecutive months.
- A trial found improved budgeting and relationship satisfaction after six months among 145 couples versus 147 controls, though its sample may not generalize.
Table of Contents
- What biblical budgeting means and how it differs from secular budgeting
- Core biblical principles that should shape any Christian budget
- Step-by-step budgeting process a Christian household can implement
- Common budgeting templates and methods Christians use
- Budgeting as a couple or family: communication and shared practice
- Common pastoral and practical questions
- Monitoring, adjusting, and spiritual practices to keep the budget working
- A practical note on what actually works for families
- Bible Money Book: a practical next step to implement a biblical budget
- FAQ
- Sources
What biblical budgeting means and how it differs from secular budgeting
Secular budgeting usually starts with a simple question: How do I keep more of what is mine? Biblical budgeting starts somewhere else entirely. Scripture frames every paycheck, home, and possession as belonging to God first, a truth rooted in the idea that "the earth is the Lord's, and everything in it." That single shift changes a spreadsheet from a restriction into an act of worship.
Consumer culture trains us to spend first and plan later, chasing comfort and status with whatever is left. A household practicing biblical stewardship reverses that order: giving, needs, and future preparation come before discretionary wants. Budgeting becomes less about restriction and more about aligning daily choices with a larger purpose.

Jesus makes the case for planning directly when he asks who would build a tower without first sitting down to count the cost. That passage does not hand us a spreadsheet template or a percentage chart. It simply makes the case that thoughtful people plan ahead, and a budget is one faithful way to do that.
Core biblical principles that should shape any Christian budget
Scripture does not prescribe a single budgeting app or category list, but a handful of principles show up again and again across financial teaching rooted in the Bible. A biblical perspective on budgeting names six themes that recur throughout these discussions, and they give us a working foundation.
- Give first and give joyfully: generosity leads the plan rather than trailing behind it, with the tithe often used as a teaching benchmark rather than a rigid legal requirement.
- Plan ahead and count the cost: the call to sit down and calculate before building, as described in Luke 14:28, applies just as well to a monthly budget as to a tower.
- Spend less than you earn: contentment, not comparison, becomes the measure of a well-lived financial life.
- Avoid excessive debt: borrowing is treated as a tool to use carefully, not a lifestyle to lean on.
- Save for the plan: future needs, from emergencies to long-term goals, get funded on purpose instead of by accident.
These principles work together. Generosity without planning drifts into inconsistency, and planning without generosity drifts into hoarding. A household that holds both in balance tends to experience budgeting as a spiritual discipline rather than a chore.
Step-by-step budgeting process a Christian household can implement
Theology matters, but a family still needs a workable process. A budgeting handout built for households walks through a sequence that translates principle into practice.
- Record take-home income. Write down the actual amount that lands in the bank each month, not the gross figure on a pay stub.
- List every expense. Include recurring bills, groceries, transportation, and anything paid only a few times a year.
- Assign categories in order: giving first, then obligations and needs, then saving and preparing, then everyday living and discretionary spending.
- Build a starter emergency fund. The same handout recommends an initial $1,000 buffer, then growing toward three to six months of expenses once consumer debt is paid down.
- Sequence debt repayment after the starter fund is in place, directing extra payments toward the highest-priority balance first.
- Review monthly. Compare what actually happened against the plan and adjust the next month accordingly.
Pro Tip: Divide annual or irregular bills, like insurance premiums or holiday giving, by 12 and set that amount aside automatically each month so one large bill never derails the entire plan.
Automating transfers for giving, savings, and bill payments removes a layer of daily willpower from the equation, which makes consistency far easier to sustain across busy seasons.
Common budgeting templates and methods Christians use
No single format is commanded in Scripture, so households are free to choose a method that fits their season of life and simply adapt it as circumstances change.
- Tithe-first percentage budgets set giving as a fixed share of income before anything else is allocated, which works well for households wanting a clear, consistent habit.
- Zero-based budgets assign every dollar a job, giving, needs, savings, and living, until income minus allocations equals zero, a strong fit for families who want full visibility.
- Envelope or cash-based systems limit spending in categories like groceries or entertainment to the physical cash on hand, which helps households prone to overspending on cards.
- 70/20/10 or similar percentage splits divide income into broad living, saving, and giving buckets, a simpler starting point for those newer to intentional budgeting.
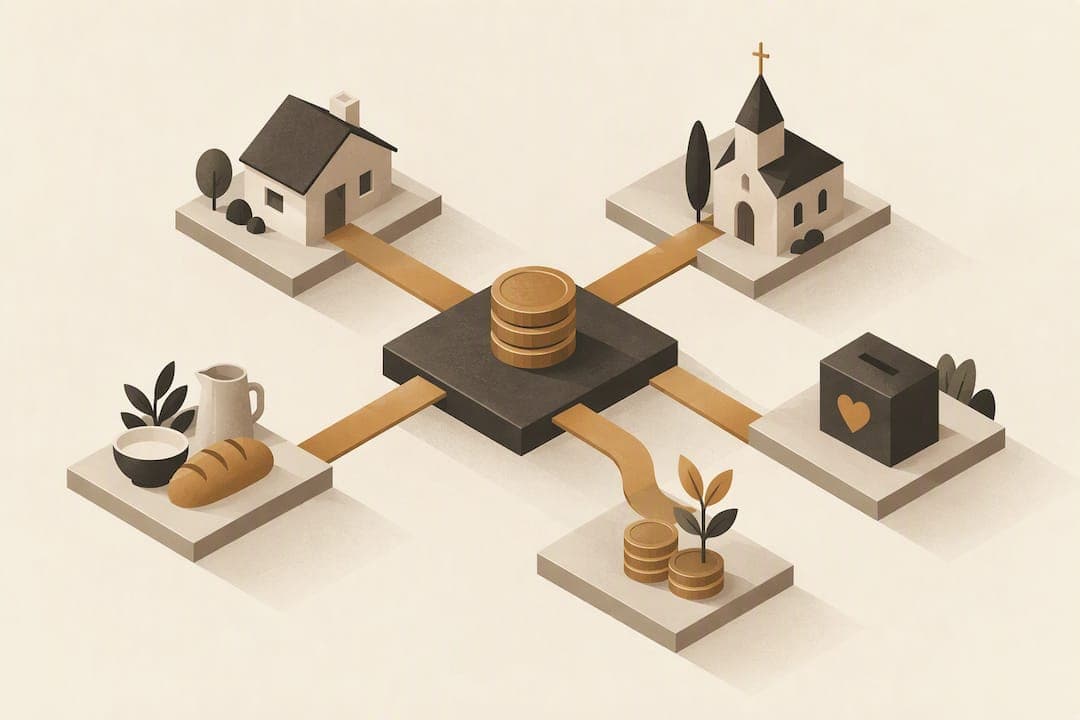
A biblical model for teaching personal finance frames these choices around four categories that should equal total income: generous giving, taxes and obligations, preparing for the future, and living joyfully today. Treat any template as a tool rather than a rule, and scale percentages up or down as household size, income stability, and season of life require.
Budgeting as a couple or family: communication and shared practice
Money decisions made alone tend to create blind spots. Research on couples shows that when one partner is excluded from financial decisions, an information gap can form, leaving that partner with weaker financial literacy over time. Shared budgeting builds resilience and continuity instead, so either spouse can step in confidently if life requires it.
A randomized trial of the TOGETHER program, which paired budgeting education with relationship skills training among 145 couples against a 147-couple control group, found meaningful improvements in budgeting behavior and relationship satisfaction at six months. The sample skewed toward lower-income, predominantly African-American couples, so results may not generalize to every household, but the pattern is encouraging for anyone wondering whether joint budgeting is worth the friction.
A simple monthly rhythm can carry this forward:
- Set a recurring date and keep it brief, 20 to 30 minutes is often enough.
- Review actual spending against the plan from the prior month.
- Ask what felt tight, what felt generous, and what fear or goal is shaping decisions right now.
Common pastoral and practical questions
Readers wrestling with real constraints deserve honest, practical answers rather than platitudes.
- Should I tithe if bills are tight? Treat generosity as a priority to grow into rather than an all-or-nothing rule. Giving a smaller, consistent percentage now while working toward a fuller tithe later honors the principle without creating unsustainable pressure.
- How do I handle existing debt? List balances from highest priority to lowest, keep minimum payments current everywhere, and direct any extra margin toward one balance at a time rather than spreading it thin.
- How do I fight comparison-driven spending? Practice gratitude for what is already provided, and keep spending decisions tied to the family's own goals instead of a neighbor's purchases.
Monitoring, adjusting, and spiritual practices to keep the budget working
A budget is a living document, not a one-time project. Monthly reviews should check whether spending matched the plan, and quarterly reviews should look at bigger trends: is the emergency buffer growing, is debt trending down, and is the percentage given staying consistent with the household's commitment.
Simple thresholds help here: a shrinking cash buffer or a rising debt balance two months in a row signals it is time to revisit categories before the gap widens. Pairing this review with a short gratitude reflection keeps the process from feeling purely mechanical. Many families also find it helpful to invite an accountability partner or small group into the conversation, and to walk children through a simplified version of the same categories so the habit carries into the next generation.

A practical note on what actually works for families
Most families do not need a more complicated system. They need a short, honest conversation and a plan simple enough to survive a busy Tuesday night. In building the Bible Money Book, the goal was never to compete with elaborate spreadsheets or financial jargon, but to give households a calm, judgment-free starting point rooted in the principles outlined above. Families who approach their finances together, even imperfectly, tend to make steadier progress than those who wait for a perfect system.
— James
Bible Money Book: a practical next step to implement a biblical budget
Reading about stewardship is one thing. Sitting down together with a plan simple enough to finish in one evening is another, and that gap is exactly what the Bible Money Book was built to close. We offer a digital guide and workbook designed to turn the principles above into a real conversation rather than another abandoned spreadsheet.

Inside, we include:
- A simplified workbook that walks through giving, needs, saving, and living categories without financial jargon.
- Conversation prompts built for couples and families who want to talk about money without tension or shame.
- A short implementation plan that turns a single evening into a working budget you can revisit monthly.
If you want additional faith-based reading alongside your budget, we also curate Business Books, Christian Coloring Books, Books & Bibles, and more for families building this habit together. Start with the Bible Money Book and have your first real money conversation this week.
FAQ
What does the Bible say about budgeting money?
Scripture frames money as belonging to God first, which means planning ahead, giving generously, and avoiding debt are treated as acts of faithful stewardship rather than optional financial tips. Passages like Luke 14:28, which describes counting the cost before building, are commonly cited as the biblical case for deliberate planning.
Should I tithe if I can't pay my bills?
Treat tithing as a priority to grow into with consistency rather than an all-or-nothing obligation that creates crisis. A smaller, sustainable giving percentage now, paired with a plan to increase it as obligations ease, honors the principle of giving first without risking essential needs.
What are some biblical principles for budgeting?
A commonly cited framework includes six core principles: everything belongs to God, give first, plan ahead, spend less than you earn, avoid debt, and save intentionally for the future. These principles are meant as formative habits rather than rigid legal rules.
What budget categories does a biblical approach use?
A practical model organizes spending into four categories that should equal total income: generous giving, obligations and taxes, preparing for future needs, and living joyfully today. This order keeps generosity and future preparation ahead of discretionary spending rather than treating them as leftovers.
Does budgeting together as a couple actually help?
Yes. A randomized trial of an integrated relationship and budgeting program found meaningful improvements in budgeting behavior and relationship satisfaction among couples at six months, though the study sample was specific and results may vary by household.
Sources
- A Biblical Model for Teaching Personal Finance (CBFA)
- Together—A couples’ program integrating relationship and financial education (RCT)
- A biblical perspective on budgeting (Stewardship UK)