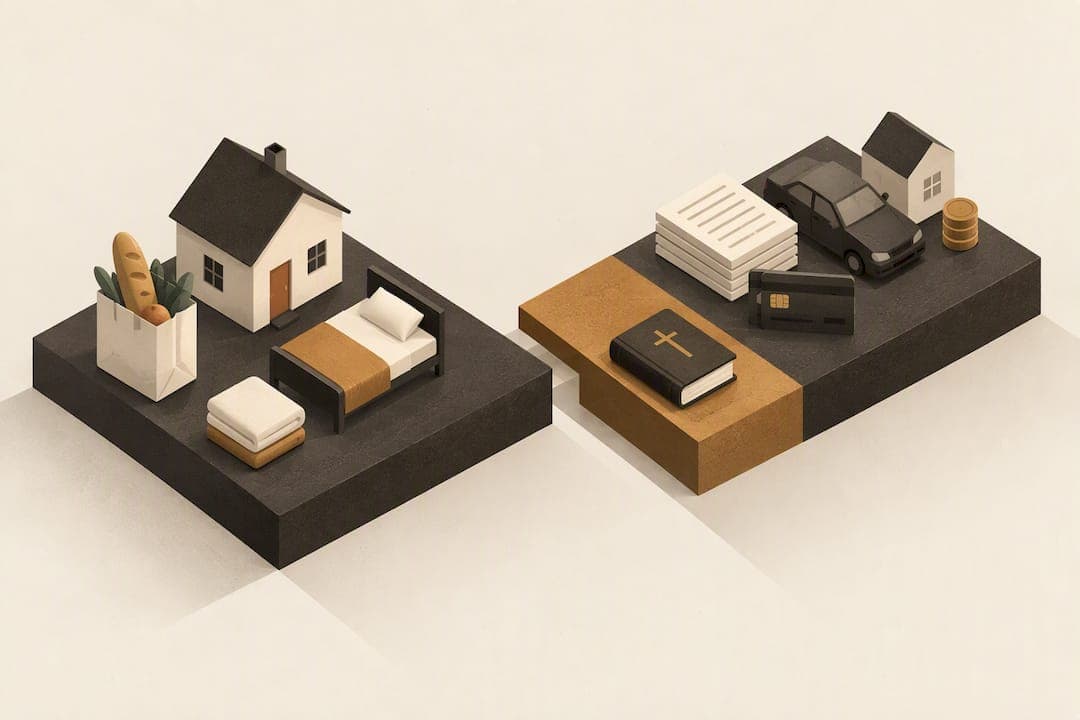
Whether you keep tithing while repaying debt usually comes down to two things: can your family cover essential needs, and can you give with a clear conscience rather than from guilt or fear? Prayerful discernment paired with a solid repayment plan points most families toward their answer. This article walks through the Scripture, the practical money steps, and a simple three-question tool to help you decide.
TL;DR:
- Cover housing, food, utilities, and basic transportation before accelerating debt payments; build one month of essential expenses before changing any other commitment, including giving.
- Choose the snowball method for quick wins by paying the smallest balance first, or use avalanche repayment to reduce interest by targeting the highest rate.
- If essentials are secure and debt stems from lifestyle spending, budget cuts may let you continue giving while speeding repayment.
- Treat borrowed funds as loans, not income, so they generally are not tithed; apply your chosen gross or net percentage consistently to earnings and windfalls.
Table of Contents
- What does the Bible say about tithing and debt?
- Budget and debt moves that protect your essentials
- Three questions that help you choose: continue, reduce, or pause
- Alternatives if a full tithe isn't realistic right now
- Where to find pastoral and practical support
- A personal take on giving through hardship
- A simple next step for your family's giving decision
- FAQ
- Sources
What does the Bible say about tithing and debt?
Scripture never directly addresses tithing while carrying modern debt, which is part of why faithful Christians land in different places. The Old Testament tithe was tied to Israel's agricultural economy and temple worship, while the New Testament shifts the emphasis toward heart-level generosity. Zacchaeus gave away half his possessions out of transformed gratitude, and the widow's two small coins mattered more to Jesus than large sums given out of abundance. Romans 13:8 adds another layer, instructing believers to "let no debt remain outstanding" except the ongoing debt to love one another, placing repayment itself inside a moral and spiritual framework.
That tension creates two honest interpretive camps:
- Some Christians treat 10% as a discipline worth protecting even during hardship, viewing it as an act of trust that God will provide.
- Others read tithing as a guideline rather than a fixed law, emphasizing sacrificial giving from the heart over a strict percentage.
- Many pastors and counselors, as Gotquestions notes, see giving as a matter of the heart rather than a tax, and some even affirm that a modest gift offered in love during severe hardship still honors God.
- A debt commitment and a giving commitment can coexist without one automatically canceling the other.
Neither camp denies that repaying what you owe matters. The disagreement is about sequencing, not about whether generosity still counts during a hard season.
Budget and debt moves that protect your essentials
Before deciding what to do about giving, get a clear picture of your finances. The CFPB's debt guidance recommends covering essential expenses, housing, food, utilities, and basic transportation, before accelerating any debt payoff or adjusting discretionary spending. If meeting those essentials is in question, that reality shapes the giving conversation more than any single verse does.
Once essentials are covered, choose a repayment strategy:
- Debt snowball: pay off your smallest balance first for quick psychological wins, then roll that payment into the next debt.
- Debt avalanche: pay off the highest-interest balance first to save the most money over time.
- Hybrid approach: start with snowball momentum, then shift to avalanche once you have built confidence.
From there, look for budget moves with real impact: canceling unused subscriptions, pausing discretionary categories for a season, and setting up sinking funds for irregular costs like car repairs or holidays. The CFPB also recommends contacting creditors directly to negotiate lower interest rates or revised payment plans rather than falling silent on an account. If debt feels unmanageable on your own, a nonprofit credit counseling agency can review your full picture and suggest a structured plan.
Pro Tip: Build one month of essential expenses before adjusting any other financial commitment, including giving. A small buffer prevents a single missed paycheck from becoming a crisis.

A simple biblical budgeting framework can help you organize these moves without turning the process into another source of shame.
Three questions that help you choose: continue, reduce, or pause
A clear decision usually comes from asking the same three questions in order, rather than wrestling with the whole issue at once.
- Can you meet essential monthly needs right now without risking eviction, shutoff utilities, or missed basic necessities?
- Is your debt emergency-driven or lifestyle-driven, and how much could trimming your budget speed up payoff?
- Have you prayed about this and talked with a pastor, elder, or trusted financial counselor who knows your specific situation?
If the answer to the first question is no, stabilizing essentials comes first. If debt is lifestyle-driven and budget changes could meaningfully accelerate payoff within a reasonable window, continuing a full or partial tithe while tightening spending elsewhere is often realistic. If you have not yet sought counsel, that conversation usually clarifies more than solitary deliberation does. Focus on the Family recommends combining spiritual discernment with practical budgeting rather than treating the two as separate tracks. Once you land on a direction, set a review date, thirty, sixty, or ninety days out, so the decision stays a living plan rather than a permanent verdict.
Alternatives if a full tithe isn't realistic right now
When that is not currently possible, a reduced but intentional "choice gift" honors the same spirit without pretending nothing has changed.
- Decide whether you are tithing on net or gross income, and apply that choice consistently so the number stays meaningful rather than arbitrary.
- For one-time sums like a bonus or tax refund, apply the same percentage you use for regular income rather than treating windfalls differently.
- Borrowed money itself is not income, so most counselors do not treat it as tithe-eligible; the tithe question applies once funds are earned or received as personal income.
- Non-monetary generosity, volunteering, meals for a struggling family, service at church, carry real spiritual weight when cash is tight.
- Write down the reduced amount, the reason, and a restart date so the adjustment feels like a plan rather than a drift.
A four-question gross-or-net checklist can help you settle the calculation question before the conversation about amount even starts.
Where to find pastoral and practical support
Talking with a pastor, elder, or trusted mentor brings a perspective that is hard to reach alone. Bring a simple budget snapshot and a list of your debts so the conversation stays concrete rather than abstract. Focus on the Family notes that pastoral counsel often helps households weigh first-fruits theology against real family obligations and timelines.
- Pair prayer and, if it fits your tradition, fasting with practical tools like a written budget.
- Use the CFPB's debt booklet alongside your pastoral conversation, not instead of it.
- A short prayer practice for financial clarity can steady the emotional side of this decision while the budget work handles the numbers.
A personal take on giving through hardship
We have seen that stewardship and compassion are not opposites. The families who navigate this best tend to pair a clear budget with grace toward themselves, refusing to let guilt dictate a number that their circumstances cannot support. A decision made in prayer, reviewed on a set date, tends to hold up better than one made in anxiety.
— James
A simple next step for your family's giving decision
If you want a guided way to work through these decisions together, the Bible Money Book offers a short, practical path. It walks couples and families through budgeting templates, conversation prompts, and devotional reflections built around the same questions covered here: what you owe, what you can give, and how to talk about both without shame.

- Conversation prompts that help couples talk about debt and giving without the discussion turning tense.
- Budgeting templates that make it easier to see essentials, debt payments, and giving side by side.
- Devotional reflections that connect each practical step back to a biblical foundation.
It costs $1 and is built for exactly this kind of decision: faith-aligned, practical, and finished in a single sitting rather than stretched across a complicated course. Visit the Bible Money Book to get started tonight.
FAQ
Do you tithe on borrowed money?
Most pastoral counselors do not treat borrowed money as tithe-eligible, since a loan is not personal income. The common guidance is to tithe on earned income or money received as income, and to apply the same percentage once borrowed funds are repaid through future earnings, as GotQuestions.org explains regarding giving as a heart matter rather than a fixed formula.
What does Romans 13:8 say about debt?
Romans 13:8 instructs believers to "let no debt remain outstanding," except the continuing obligation to love one another. This places repaying what you owe within the same moral framework as generosity, rather than treating the two as competing priorities.
How much is a tithe on $10,000?
A tithe is traditionally 10% of income. The exact amount depends on whether you calculate it on gross or net income after taxes, so clarifying your basis helps keep the figure consistent.
Who is exempt from tithing?
Many counselors, including guidance summarized by Focus on the Family, suggest that households facing genuine inability to meet essential needs may reduce or temporarily pause giving while still aiming to remain generous in some form.
Sources
- Gotquestions
- Bible Gateway — Romans 13:8-10 (AMPC)
- CFPB — Your Money, Your Goals: Debt booklet
- Focus on the Family — Tithing and giving while in debt